Mortgage broker in Geneva: finance your property purchase

- The property price can completely change the bank’s calculation
- The value used by the bank matters as much as the agreed price
- What a mortgage broker checks before sending your file to lenders
- Geneva has specific features that can affect mortgage financing
- Our approach to financing your property purchase in Geneva
- Preparing the right documents helps avoid repeated follow-ups
- Comparing mortgages is about more than the interest rate
- Frequently asked questions about mortgage financing in Geneva
Buying an apartment or house in Geneva often creates a particular challenge: financing can become restrictive long before the mortgage rate is the main issue.
When the property price is high, having 20% equity is not necessarily enough. The bank also checks whether your income can sustainably support the mortgage under its own affordability criteria, using a theoretical interest rate that is significantly higher than the rate actually offered.
The role of a mortgage broker in Geneva is therefore not simply to find a rate a few tenths of a percentage point lower. The first task is to determine how to present your project to lenders that are likely to accept it, and then compare their financing terms.
In Geneva, the property price can completely change the bank’s calculation
Let’s take a deliberately simplified example.
For a property purchased for CHF 1’200’000 with CHF 240’000 in equity, the mortgage amounts to CHF 960’000.
Even if the rate actually offered by the bank is much lower, the lender may test your affordability using a theoretical rate close to 5%, generally adding theoretical maintenance costs and any required amortisation of the second- rank mortgage.
In this example, theoretical annual housing costs can quickly exceed CHF 70’000. If the bank wants them to remain around one third of gross income, the required annual income can exceed CHF 200’000.
The exact parameters vary between lenders, but this example shows why, in a market such as Geneva, securing a good rate does not necessarily solve the main financing issue.
Sometimes the first priority is the financing structure.
The value used by the bank matters as much as the agreed price
Another issue is often underestimated when buying property: the bank does not necessarily finance the property on the basis of the price you agreed to pay.
It carries out or uses its own valuation of the property.
If you buy an apartment for CHF 1’300’000 but the lender uses a lower lending value , the financing may be calculated on that lower bank value rather than simply on the purchase price.
The difference does not automatically become additional mortgage financing. It may have to be covered with more equity.
That is why it is particularly useful to have the feasibility of the financing checked before signing an irreversible purchase commitment or paying a non-refundable deposit.
Two lenders may also assess the same property or the same application differently. Choosing a lender therefore depends on more than the advertised interest rate.
What a mortgage broker checks before sending your file to lenders
An effective mortgage application is not about sending the same documents to ten lenders and hoping that one of them says yes.
Before comparing lenders, the broker analyses in particular:
- the property’s value and purchase price;
- the source and composition of your equity;
- your fixed income and, where applicable, the variable portion of your remuneration;
- your loans, leasing commitments, maintenance payments or other financial obligations;
- the possible use of your 2nd pillar or pillar 3a ;
- the need to amortise part of the mortgage;
- your affordability under the criteria applied by lenders;
- the mortgage strategy planned after the purchase.
Above all, this analysis helps avoid approaching lenders whose criteria do not match your situation.
Geneva also has specific features that can affect mortgage financing
Not every property purchase in Geneva should be handled in the same way.
Before approaching lenders, it may be necessary to identify the specific legal or financial regime applying to the property and the buyer.
A condominium in a development zone is not an ordinary condominium
Certain condominium units located in a Geneva development zone are subject to cantonal control of the sale price.
The maximum authorised price may then result from a specific process involving the Cantonal Office for Housing and Land Planning (OCLPF). For the condominiums concerned, the sale price is subject to state control and a provisional sale approval forms part of the process before the sale is signed. For condominiums built in a development zone, the state control of the sale price applies for 10 years from the average move-in date of the first owners.
For the buyer, this means it is useful to establish very early whether the desired property falls into this category. The available documents, regulated price and conditions attached to the property must be correctly incorporated into the file submitted to the lender.
Mortgage financing should therefore not be prepared solely on the basis of the property listing and the price agreed with the seller.
Insufficient equity: a Geneva-specific option worth checking
Geneva also has a cantonal home-ownership support mechanism for certain buyers of a primary residence.
Subject to meeting the legal requirements, a person with at least 5% of the purchase price of their future primary residence may, in certain situations, apply for a loan from the Canton of Geneva which can make up as much as 15% of missing equity.
This option does not mean that a purchase automatically becomes financeable: affordability, the property and all of the lender’s criteria must still be validated.
However, for a household abandoning its project solely because it does not meet the equity normally required, it is worth checking this option before concluding that the purchase is impossible.

Our approach to financing your property purchase in Geneva
Our objective is not to send your application to as many lenders as possible.
We first seek to understand your project and identify financing solutions that fit your situation.
The process has three stages:
- You describe your property project to us, the property price, your income, your equity and your timetable.
- A partner mortgage broker analyses your financing capacity and identifies any points that need to be clarified or strengthened before approaching lenders.
- The relevant lenders are then compared on the basis of their terms: interest rate, term, amortisation, flexibility, fees and options for future adjustments.
For private individuals, our introduction and brokerage service is non-binding. The broker is remunerated by the lending institutions when financing is completed.
Preparing the right documents mainly avoids unnecessary back-and-forth
For an initial assessment, prepare in particular your latest payslips, recent tax return, evidence of your equity, occupational pension statement and pillar 3a statements if you intend to use them.
Once the property has been identified, you will also need to provide property documents: the sales file, land-register extract, plans, condominium information for an apartment and, depending on the project, any additional documents requested by the lender.
The final list depends on your profile and the property being financed.
The benefit of preparing a file in advance is less about “making a good impression” than enabling the lender to make a decision without repeatedly interrupting its assessment to request missing information.
Comparing mortgages is about more than the interest rate
Two offers showing almost the same rate can have very different consequences a few years later.
You should look in particular at the contract term, options for changing or repaying the mortgage, the structure of the mortgage tranches, the amortisation rules, the conditions applying if the property is sold and the margin added by the lender for a SARON mortgage.
An offer that is slightly cheaper today can become more expensive if it imposes a structure that is poorly suited to your project.
The broker should therefore compare the financing as a whole, not just the first line of an interest-rate table.
What our clients say
Frequently asked questions about mortgage financing in Geneva
Should you wait until you have found a property before contacting a mortgage broker?
No. It is often better to have your situation assessed before starting your property search. You will then know your realistic budget and any issues in your application that should be addressed before making an offer.
If you have already found a property, contact the broker before signing a purchase commitment or paying a non-refundable deposit.
Why might the bank finance less than 80% of the purchase price?
Because the price paid and the value used by the bank are not necessarily the same.
If the lender values the property below the purchase price, it may calculate the financing on that lower value. The buyer will then generally need additional equity to cover the difference.
Can you buy in Geneva with less than 20% equity?
In certain situations, a loan from the Canton of Geneva designed to supplement equity may be considered for the purchase of a primary residence.
It is subject to specific conditions and does not replace the bank’s affordability assessment. Eligibility for the scheme and the feasibility of the mortgage financing therefore need to be assessed together.
How much does your mortgage brokerage service cost?
For private individuals, our support is non-binding and is not charged to the client when financing is completed through our service. The broker is remunerated by the lending institution when the financing is concluded.
Fixed or SARON mortgage: which should you choose in Geneva?
The property’s location does not determine the mortgage model.
The choice mainly depends on your budget, your holding period, your ability to absorb changes in interest costs and the degree of flexibility you want.
Rather than automatically choosing the lowest rate currently available, it is better to compare several financing scenarios and their impact on your budget.
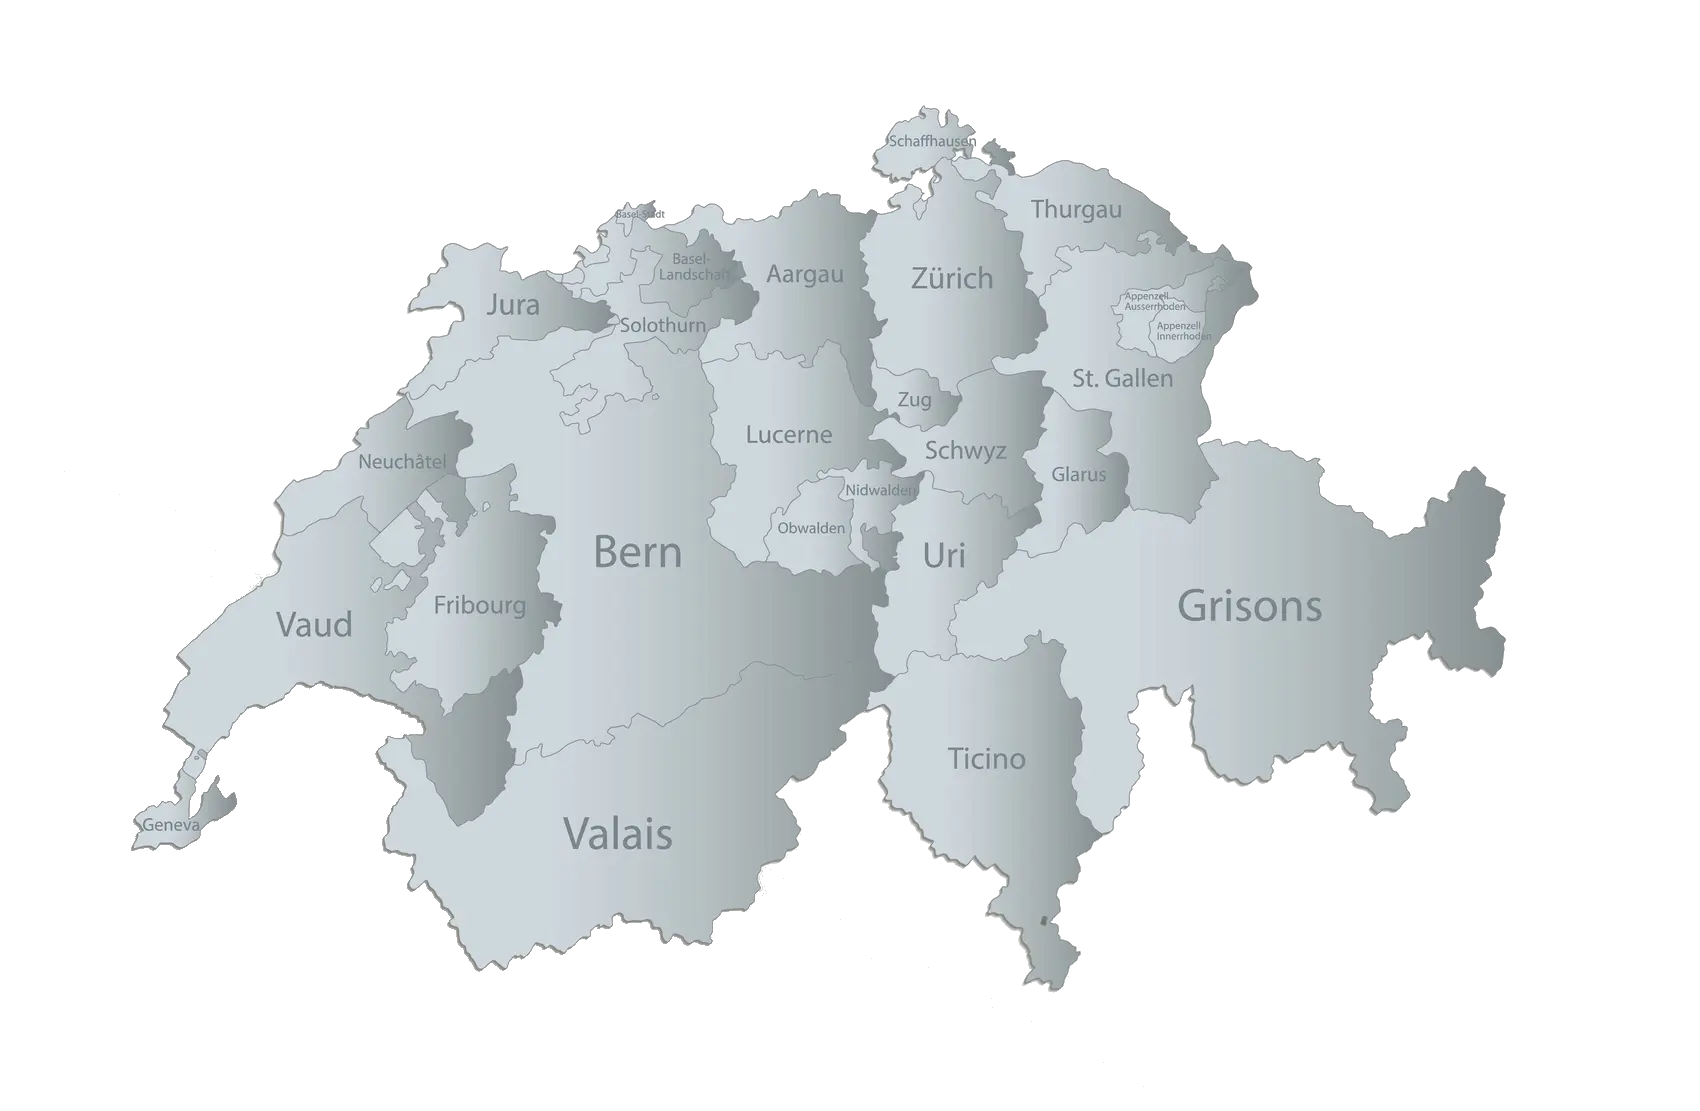
Find us throughout Switzerland
Zoomez et cliquez sur le canton désiré.
Disclaimer: The information presented on this page is provided for informational purposes only and does not constitute a financing offer or personalised legal, tax or financial advice. Mortgage lending criteria, property valuation methods and financing conditions may vary between lenders and change over time. The Geneva cantonal measures mentioned, including home-ownership support and the rules applying to certain condominiums located in development zones, are subject to specific legal and administrative conditions. Their applicability must be verified on a case-by-case basis with the competent authorities and the financial institutions concerned.