Trends in mortgage rates in Switzerland: everything you need to know for 2025

- A look back at the historical evolution of mortgage rates in Switzerland
- The impact of the mortgage interest rate on a home loan
- Why it’s important to plan your mortgage application ahead
- How did Swiss mortgage rates evolve in 2025?
- How did monetary policy evolve in 2025?
- What factors influence mortgage rates?
- Fixed, variable or mixed mortgage: how to choose?
- Frequently asked questions about mortgage rates
Are you planning to buy a property, renegotiate your loan or simply understand the market better? Are you wondering whether rates will rise, fall or stabilise in the coming months? You’re in the right place!
Mortgage rate trends in Switzerland directly influence the cost of your loan and your purchasing power. These rates depend on many factors: SNB policy, inflation, economic conditions, market pressure…
Here’s a clear and complete overview of the history of Swiss rates, current trends and forecasts, and the concrete impact of these fluctuations on your mortgage.
Editorial note: This article was written in 2024 to examine the outlook for the Swiss mortgage market for 2025 and to help prospective buyers decide whether to purchase in 2024 or wait until 2025. It retains this historical perspective. Consequently, the forecasts and scenarios presented should be interpreted within the economic and monetary context that existed at the time of publication. For an overview of the outlook and market conditions in 2026, consult our guide to mortgage rate trends in Switzerland in 2026.
A look back at the historical evolution of mortgage rates in Switzerland
Over the past 20 years, Swiss mortgage rates have shown a marked downward trend, especially after the 2008 financial crisis. This drop was driven by the Swiss National Bank’s (SNB) very accommodative monetary policy, with a key rate close to zero or even negative for several years.
Between 2010 and 2020, 10-year fixed rates were often between 1% and 2%, sometimes even dipping below 1%.
2022–2023 marked a turning point, with a gradual rise in mortgage rates due to the rebound in global inflation and rate hikes by major central banks.
The impact of the mortgage interest rate on a home loan
The interest rate directly affects the total cost of your mortgage loan. Even a small difference of 0.5% can amount to several thousand francs over the repayment period.
Monthly payments
The higher the rate, the higher your monthly payments. For example, for a CHF 800,000 loan over 10 years:
- At 1.5%, total interest will be around CHF 120,000
- At 2.5%, it will climb to over CHF 200,000
This differential impacts your monthly budget, but also your ability to invest or save for other projects.

Borrowing capacity
Lenders take the rate into account when calculating your debt capacity. A high rate can reduce the maximum amount you can borrow, or lengthen the loan term needed to stay within set limits.
Why it’s important to anticipate your mortgage application
In an unstable economic context, locking in a good rate at the right time can make all the difference. That’s why working with a broker who monitors markets daily and helps you choose the best strategy according to your goals is valuable.
Also, before signing your loan, compare several offers and simulate the impact of different rate scenarios. Signing too quickly without comparing can unnecessarily increase your financial burden. Our brokers support you at every step to make the right choice, at the right time, with full transparency.
By anticipating, you can prepare financially and have a better chance of securing a favourable mortgage loan.
How did Swiss mortgage rates evolve in 2025?
In 2025, the Swiss mortgage market was shaped by the Swiss National Bank’s monetary policy easing, with its policy rate reduced to 0% effective 20 June. This development influenced short-term financing conditions without automatically causing an equivalent decline in fixed mortgage rates.
The rates offered to borrowers also depended on the selected mortgage term, swap rates, lenders’ margins and the characteristics of each financing application.
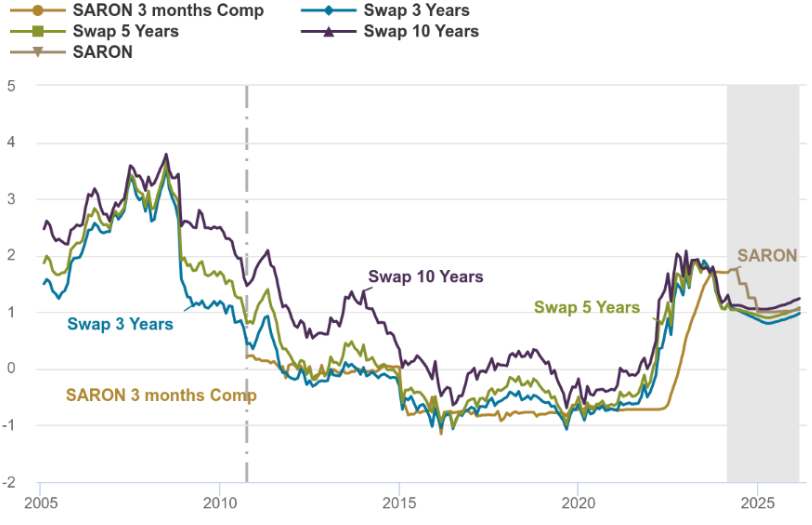
Rate evolution in % | Sources: Bloomberg, UBS Switzerland SA (This is an indicative interest rate. The effective interest rate is calculated from the margin and the Compounded SARON of the counting period. Compounded SARON cannot be negative.)
Here is how to interpret this chart:
SARON:
- Money market base → changes daily.
- If you take a SARON mortgage, you pay: SARON + bank margin (~0.8% to 1.5%).
SWAP:
- Allows a bank (or you indirectly) to lock this variable rate over a given period.
- Example: SARON swap → fixed rate for 5 years.
- The longer the duration, the more the swap rate includes a time risk premium.
How is a fixed mortgage rate determined?
Fixed mortgage rates are influenced in particular by swap rates for the corresponding terms, refinancing costs and lenders’ margins. They may therefore change even before the Swiss National Bank adjusts its policy rate.
SARON mortgages, on the other hand, are based on a money market reference rate to which a contractual margin is generally added.
How did monetary policy evolve in 2025?
The year 2025 saw a further easing of Swiss monetary policy. On 19 June 2025, the Swiss National Bank announced a reduction in its policy rate to 0%, effective 20 June. It subsequently maintained the rate at 0% at its monetary policy assessment on 25 September 2025.
This development helped keep short-term financing conditions favourable. However, fixed mortgage rates also depend on financial market expectations and do not necessarily move in line with SNB policy decisions or by the same amount.
Which factors influence mortgage rates?
Several elements determine the rates offered by banks and other financial institutions:
- SNB monetary policy: its key rate guides refinancing costs for banks
- Inflation: rising prices generally push rates up
- Overall economic conditions: growth, employment, geopolitical tensions…
- Risk level of the file: personal contribution, income, job stability, type of property financed
Each borrower therefore has a unique profile that will influence the conditions obtained. You are unique, and your file must reflect that. Your happiness in your home or apartment depends on it.

Fixed rate, variable rate, or mixed mortgage: how to choose?
Mortgage rates have a direct impact on your financial decisions: overall budget, purchasing power, choice between fixed rate or SARON… A variation of a few tenths of a point can represent several thousand francs in the long term. Also, regularly monitoring their evolution allows you to anticipate the best times to borrow or renegotiate your loan, and prepare for possible market fluctuations (especially if you opt for a variable rate or if your contract is about to expire).
The choice of rate type depends on your profile, risk tolerance, and wealth strategy.
| Mortgage type | Advantages | Disadvantages |
|---|---|---|
| Fixed rate | Security Stable monthly payments, Ideal for tight budgets | Less flexibility Rates often higher than SARON |
| SARON rate* | Lower initial rate Potential savings if rates fall | Revised every 3 months Risk of unexpected increase |
| Mixed mortgage | Combines stability and opportunity | More complex to manage |
*SARON is recalculated every business day and applied on average every 3 months. It is therefore more volatile but can be interesting if you anticipate a rate decrease in the medium term.
Feel free to contact one of our mortgage brokers for personalized advice and use our online simulator for a quick, free, and non-binding first personalized estimate.
Frequently asked questions about mortgage rates
How does rate fluctuation impact my mortgage loan?
A rate increase raises the overall cost of credit, especially for variable mortgages. A 2% rate instead of 1.5% on a loan of 800,000 CHF can represent several thousand francs extra over the term.
What is the current key interest rate?
The current SNB policy rate, currently published on the SNB web site, primarily influences short-term money market conditions. It is not the interest rate borrowers pay on a fixed-rate or SARON mortgage. Lenders also take into account their refinancing costs, margins, the mortgage term and the borrower’s individual risk profile.
The SNB policy rate should not be confused with the Swiss mortgage reference interest rate used under tenancy law.
When is the right time to borrow?
The “right time” depends on your project. Rather than waiting for a hypothetical rate drop, it is better to secure an attractive offer as soon as you are ready to buy. Rates can move quickly.
Will mortgage rates increase?
It is impossible to predict the future direction of Swiss mortgage rates with certainty. Their evolution depends on several factors, including Swiss National Bank (SNB) monetary policy, inflation, financial market expectations and international economic conditions.
Fixed mortgage rates can rise or fall even without a change in the SNB policy rate, particularly in response to movements in swap rates and refinancing costs.
Rather than trying to time the market perfectly, it is advisable to compare several offers, simulate different interest rate scenarios and choose a financing solution suited to your financial circumstances. Our mortgage advisers can support you throughout this process.
How to choose the right lending institution?
Each bank applies its own pricing grids. The best rate is not everything: repayment conditions, flexibility, support are also to be compared. A broker can help you play the competition.
What is the difference between the advertised rate and the personalized rate?
The advertised rate by banks is often indicative. The personalized rate depends on your profile (income, equity, type of property, financing ratio, etc.). It can be more advantageous if your file is solid. Hence the benefit of going through a broker to negotiate better.
Can a mortgage be renegotiated before maturity?
Yes, it is possible in some cases, especially near the end of the contract. You can also consider a refinancing with another bank. It is important to take into account any early exit penalties. A broker can help you make the right calculations.
Can the SARON rate exceed the fixed rate?
Yes, it is possible, especially during periods of rapid increases in key interest rates. SARON is indexed on short-term Swiss money market rates, so it can vary upwards. This represents a risk for borrowers seeking stability.
Can I change the type of rate during the contract?
It depends on the initial contract. Some mortgages offer a conversion option (for example, switching from a SARON rate to a fixed rate). But it is not systematic. You must check the terms of your contract or consult a broker before signing.