Finance your project with a professional mortgage broker
- Why use a mortgage broker?
- Our mortgage brokerage service in Switzerland
- Your mortgage financing in six steps
- Why do banks not all reach the same result?
- What a broker should compare beyond the interest rate
- How much does our mortgage brokerage service cost?
- Does remuneration by the lender create a conflict of interest?
- What you gain in practical terms with a mortgage broker
- In which situations does a broker add the most value?
- Which documents should you prepare for your application?
- When should you contact pretimmobilier.ch?
- Frequently asked questions about mortgage brokers
A mortgage broker does more than look for an attractive interest rate. The broker analyses your situation, checks the consistency of the financing, prepares your application and selects institutions whose criteria genuinely match your profile and the property.
With pretimmobilier.ch, you benefit from a free, no-obligation initial consultation (the rest of the process is also free of charge for you). We assess your project and then direct you to the partner in our network with the most relevant experience and access to handle your application.
Why use a mortgage broker?
When you contact a lender directly (bank, insurance company or pension fund), it assesses your application according to its own rules, products and risk policy. It may advise you properly, but it does not compare its proposal with those of its competitors.
A broker’s role is different. The broker seeks a solution from several lenders and presents your application to contacts likely to finance it. The work covers all of the following:
- the feasibility of your purchase;
- the amount you can reasonably borrow;
- the composition of your equity;
- how your income will be recognised;
- the valuation of the property;
- the choice of mortgage model;
- contractual terms and fees;
- the timetable required to obtain financing.
The interest rate is therefore only one part of the decision. A slightly cheaper offer may become disadvantageous if it imposes a long, inflexible term, expensive ancillary products or a high penalty in the event of an early sale.
Our mortgage brokerage service in Switzerland
pretimmobilier.ch is not a bank and does not grant credit directly. Our role is to understand your project, identify its particular features and select the professional best placed to present and support your application.
This organisation avoids a common weakness of referral platforms: automatically sending the same application to several advisers without considering their specialisation.
Financing a primary residence in Geneva is not necessarily handled in the same way as a rental investment in Fribourg, a second home in Valais or the purchase of an older building requiring substantial work. The type of property, region, amount sought, income and timetable can change the list of potential lenders.
Your mortgage financing in six steps
1. We assess your property project
The initial contact is handled by pretimmobilier.ch. It enables us to gather the essential information without immediately asking you for a complete bank application.
In particular, we seek to establish:
- whether it is a primary residence, a second home or an investment property;
- whether you have already found the property;
- the canton and municipality in which it is located;
- its approximate price;
- the amount you wish to borrow;
- the equity available to you;
- your employment situation;
- the deadline by which the financing must be confirmed.
This assessment avoids assigning your project to a generalist when your application requires specific expertise.
2. We select the right partner
After this initial discussion, we choose the partner in our network who best matches the application. The selection may depend on the partner’s operating region, relationships with certain lenders, experience with atypical income or expertise in a particular type of financing.
For example, a partner accustomed to applications from employees will not necessarily be the most suitable person to analyse the accounts of a company owned by the borrower. Likewise, a broker specialising in primary residences does not always have the same access for financing rental properties.
We therefore seek the right fit between the client, the property and the specialist responsible for the application.
3. The broker prepares your financing application
The selected partner then takes over. The partner gathers the supporting documents, checks their consistency and calculates your affordability.
Affordability is the relationship between the property’s theoretical costs and the sustainable income recognised by the lender. To make this calculation, institutions generally do not rely solely on the rate actually offered. They often use a long-term imputed rate of around 4.5% to 5%, plus amortisation and estimated maintenance costs and charges. Permissible costs are usually around one third of the relevant income, but each lender retains its own rules.
The broker also examines the source of the equity, existing financial commitments and income stability. An application must not only be complete: the figures, documents and explanations must tell the same story.

4. The broker develops a financing strategy
Before requesting offers, the broker determines how to structure and present the financing. This step is often overlooked when the buyer contacts several banks directly.
The strategy may cover:
- the amount of equity to commit immediately;
- withdrawal or pledging of pension assets;
- direct or indirect amortisation;
- the allocation between a fixed rate and a SARON mortgage;
- the contract term;
- the number of tranches;
- taking rental income into account;
- financing renovation or construction work;
- affordability after retirement.
In Switzerland, a primary residence is generally financed up to a maximum of 80% of its lending value. At least 10% of this value must come from equity that does not originate from a withdrawal from the 2nd pillar. In principle, the debt must be reduced to two thirds of the lending value within no more than fifteen years, or sooner when retirement requires a shorter horizon.
These figures are general rules, not an entitlement to financing. A lender may require more equity or faster amortisation depending on the property and the borrower’s profile.
5. The application is submitted to relevant lenders
A serious broker does not automatically send your application to every available institution. The broker first identifies those whose credit policy is compatible with your situation.
Banks, insurance companies and pension funds do not necessarily finance the same types of property. Some lenders favour primary residences and long-term fixed-rate mortgages. Others accept more rental financing, construction loans or SARON solutions. Restrictions may also concern the region, minimum amount, loan-to-value ratio or type of property.
The right lender is not simply the one advertising the lowest rate. It is first and foremost the lender that can finance the property, correctly recognise your income and offer a contract consistent with your future plans.
6. You compare the proposals and decide
The broker analyses the responses received and explains the differences. You remain free to accept or reject a proposal.
Once an offer has been selected, the broker coordinates the steps required through to completion of the financing: conditions to be met, additional documents, credit confirmation, liaison with the notary and release of funds.
Why do banks not all reach the same result?
The minimum rules for mortgage financing are common to a large part of the market, but their implementation is not. Lenders define their valuation methods, imputed interest rate, accepted income and affordability limits in internal guidelines.
As a result, an application may be rejected by one institution and accepted by another without either necessarily having made an error. Their assessment of the risk may simply differ.
Recognition of income
A fixed salary paid for several years is relatively straightforward to document. The following situations require more analysis:
- variable bonuses or commissions;
- overtime;
- self-employment;
- income from several employers;
- foreign income;
- dividends paid by the borrower’s own company;
- rental income;
- maintenance payments;
- income expected to decrease on retirement.
An institution may use the average from several financial years, apply a discount to variable income or disregard it entirely. The broker must therefore understand the lenders’ approach before submitting the application.
The value used for the property
The price agreed with the seller is not automatically the value accepted by the bank. For a property purchase, the lender generally applies the lower-of-cost-or-market principle: it uses the lower of the purchase price and its own estimate of market value.
Suppose you buy a property for CHF 1’000’000.–, but the lender values it at CHF 900’000.–. Maximum financing of 80% would then be calculated on CHF 900’000.–, i.e. CHF 720’000.–.
You would therefore need to contribute CHF 280’000.– in equity to cover the difference between the purchase price and the credit granted. That is CHF 80’000.– more than the CHF 200’000.– required if the property had been valued at the purchase price. Unfinanced acquisition costs would be added to this amount.
Good preparation makes it possible to identify this risk before making a commitment that may be difficult to meet.
The property’s characteristics
The lender also considers whether the property could be resold under normal conditions if the loan were no longer serviced. Its analysis may be influenced by:
- the location and local demand;
- the building’s general condition;
- planned renovations;
- energy performance;
- floor area and layout;
- a commercial component in the building;
- a building right;
- a plot that is very large in relation to the dwelling;
- insufficient rental income;
- unauthorised work;
- condominium ownership with an insufficient renovation fund.
The broker cannot change the property’s characteristics, but can avoid submitting it to lenders that exclude such properties from the outset.
What a broker should compare beyond the interest rate
Two offers with the same rate and the same amount are not necessarily equivalent. A professional comparison must include clauses that may have a financial impact throughout the contract term.
The mortgage model
A fixed-rate mortgage offers a stable contractual rate for a defined period. A SARON mortgage consists of a reference rate linked to the money market plus a margin set by the lender.
The choice should depend on your tolerance for fluctuations, your financial reserves, your expected holding period and the flexibility you require. It should not be based solely on the lowest rate on the day of comparison.
Term and maturity dates
A long term improves budget predictability but often reduces the freedom to change strategy. A short term offers greater flexibility, with the risk of having to renew in a less favourable interest-rate environment.
Splitting the mortgage into several tranches can reduce the risk of having to renew the entire mortgage at the same time. It can also lock you into the lender if the maturity dates are too far apart: a new institution will rarely take over a single tranche without controlling the entire financing. A large gap between maturities can therefore make a transfer to a competitor more difficult.
Exit conditions
A sale, divorce, move or career change may force you to alter the financing before maturity. Early termination of a fixed-rate mortgage can result in a substantial penalty, calculated in particular according to the amount, remaining term and market conditions.
Before signing, you should therefore check:
- the terms for transferring the mortgage to another property;
- the consequences of a sale;
- the treatment of early repayment;
- administrative fees;
- the options for changing mortgage model;
- notice periods.
Fees and ancillary relationships
Some lenders charge valuation, application, amendment, renewal or mortgage-note transfer fees. Others make a discount conditional on opening an account, transferring investments or taking out a pension product.
These factors do not automatically make an offer poor. They must, however, be quantified and included in the comparison. Mortgage-related fees of several hundred francs may be added to the interest depending on the provider and transaction.
How much does our mortgage brokerage service cost?
Our service is free for the client. You do not pay pretimmobilier.ch any fees for assessing your project, selecting the partner or making the introduction.
When the financing is completed, the selected lender pays a commission to the professional who introduced and handled the application. pretimmobilier.ch is remunerated through this commercial relationship, either directly or through the partner responsible for the financing.
This is therefore not unpaid work: the service is funded by the lender rather than billed to the borrower.
How much is the commission?
There is no single commission rate for all brokers and all Swiss institutions. The scales depend in particular on the lender, amount, product, term and sometimes the volume of business introduced.
Information published by some market participants generally refers to a commission of approximately 0.3% to 1% of the mortgage amount. This range is indicative and is not an official tariff applicable to every application.
For example, a 0.5% commission on a mortgage of CHF 800’000.– amounts to CHF 4’000.–. This amount is paid by the lender; our services do not issue you a corresponding brokerage invoice.
Why does a lender agree to remunerate a broker?
The broker brings the lender a client whose project has already been assessed. The broker gathers the documents, clarifies the particular features of the application and reduces some of the prospecting and preparation work.
For the lender, this commission is therefore an acquisition and distribution cost. For the client, this model provides professional support without adding brokerage fees to the already significant costs of the purchase.
Does remuneration by the lender create a conflict of interest?
The question is legitimate. Commissions can vary between institutions. It would therefore be inaccurate to claim that no potential conflict exists.
Our answer is based on the method used:
- pretimmobilier.ch selects the partner according to the characteristics of the application;
- lenders are targeted according to their ability to finance the client and the property;
- offers are analysed on their overall terms, not solely on the commission or advertised rate;
- the client receives the explanations needed to make a decision;
- the final choice always belongs to the client;
- no financing decision is imposed.
We do not claim to automatically compare every lender active in Switzerland. A genuinely useful comparison covers institutions that are accessible and relevant to the application concerned.
Our objective is to present you with a financeable, understandable solution suited to your long-term project.

What you gain in practical terms with a mortgage broker
A budget checked before you commit
An online simulation provides an initial estimate, but it cannot always recognise a bonus, assess a self-employed person’s accounts, measure the effect of retirement or anticipate a difference between the purchase price and the bank’s valuation.
The broker compares the theoretical budget with the reality of the application. This check is particularly useful before signing a reservation, making a binding offer or committing to a seller.
An application presented to the right contact
Contacting ten institutions without a strategy is not necessarily more effective than approaching three that have been correctly selected. A targeted application reduces unnecessary steps and focuses negotiations on lenders that are likely to proceed.
A better understanding of bank decisions
A bank rejection does not always mean the project is impossible. It may result from the lender’s internal policy, a missing document, a conservative property valuation or an unfavourable method of calculating income.
The broker identifies the obstacle and determines whether it can be corrected, explained or presented to another institution.
A contractual comparison, not just a price comparison
You receive a structured review of the proposals: rate, term, SARON margin, amortisation, fees, guarantees, exit conditions and ancillary products.
One point of contact throughout the process
The broker follows up document requests, questions from credit analysts and sale-related deadlines. You avoid having to repeat the same explanation to every institution.
You retain decision-making power
You do not delegate the decision. You delegate the analysis, search and negotiation. You remain free to choose the offer, request further explanations or decide not to proceed.
In which situations does a broker add the most value?
Brokerage can be useful for a standard application, but its value becomes particularly apparent when the financing involves a difficulty or several variables.
First property purchase
A first purchase means having to understand affordability, equity, the mortgage note, amortisation, the notarial process and interest-rate models at the same time. An experienced contact helps put each decision in the right order.
Self-employment or variable income
Annual accounts, salaries paid by the borrower’s own company, dividends and fluctuations in profit must be analysed according to the lender’s rules. The choice of institution can have more impact than a few hundredths of a percentage point on the rate.
Second home
Loan-to-value ratios are often more conservative than for a primary residence. In principle, 2nd-pillar assets cannot be withdrawn to finance a holiday home, and some lenders do not accept this type of property.
Rental investment
The lender analyses the yield, sustainable rents, costs, potential vacancy and the income value. High personal income on the buyer’s part is not sufficient on its own.
Purchase with renovation work or construction
The financing must distinguish between the price of the land or building, the work, reserves and successive drawdowns. The expertise required and the lenders available are not the same as for the purchase of a completed property.
Approaching retirement
Affordability must remain acceptable after the foreseeable reduction in income. It may be necessary to increase equity, plan additional amortisation or reconsider the target price. It is advisable to address this issue several years before retirement.
Refinancing or renewal
Waiting for the current lender’s renewal offer before starting the renewal process reduces the time available to compare and transfer the financing. The search should generally begin several months before maturity, taking account of the notice period and options for fixing a rate in advance. Depending on the contract and lender, preparation six to eighteen months before maturity may be appropriate. Transferring your mortgage from one bank to another before maturity is called refinancing or a mortgage transfer.
Which documents should you prepare for your application?
The exact documents vary depending on the project. An initial list nevertheless helps save time.
For employed borrowers
- identity document or residence permit;
- salary certificates;
- latest payslips;
- latest available tax assessment;
- recent extract from the debt enforcement register;
- pension certificates;
- proof of equity;
- documents relating to existing loans, leases or maintenance payments.
For self-employed persons or company directors
- annual accounts for several financial years;
- tax returns and tax assessments;
- extract from the commercial register;
- recent interim accounts if necessary;
- details of shareholdings and shareholder loans;
- proof of salaries and dividends.
For the property
- sales documentation;
- land register extract;
- plans and floor areas;
- building insurance policy;
- list of renovations;
- quotes for planned work;
- condominium ownership documents;
- status of the renovation fund;
- leases and rent schedule for an investment property.
An extract from the debt enforcement register less than six months old is commonly among the documents requested for a mortgage.
When should you contact pretimmobilier.ch?
Before you have found a property
A budget assessment enables you to search within a realistic price range. It prevents you from viewing properties that your affordability would not permit you to finance or, conversely, from underestimating your room for manoeuvre.
Once you have found the property
Contact us as soon as you have the sales documentation, price and proposed timetable. A verbal assurance from an institution is not a substitute for confirmation based on an analysis of both the client and the property.
Before renewing your mortgage
Send us the amounts, models, maturity dates and notice periods for your tranches. We can determine whether competitive tendering, restructuring or remaining with the current lender should be considered.
Frequently asked questions about mortgage brokers
What is a mortgage broker?
A mortgage broker is an intermediary specialising in property finance. The broker analyses the borrower’s application, identifies suitable lenders, requests proposals and supports the client through to completion of the loan.
What is the difference between a mortgage broker and a bank?
A bank offers the products it finances itself. A mortgage broker seeks a solution from several institutions. However, the broker does not decide whether to grant the loan: that decision belongs exclusively to the lender.
Is the service really free?
Yes. pretimmobilier.ch does not charge you a fee for assessing the project and putting you in contact with a partner. When the financing is completed, the remuneration comes from the selected lender, either directly or through the partner handling the application.
Can the mortgage broker guarantee the lowest rate in Switzerland?
No. Such a guarantee would not be credible. The rate depends on the market, the date, the property, the amount, the loan-to-value ratio, affordability and the lender’s policy. The objective is to obtain competitive, suitable terms from institutions relevant to your application.
How many proposals will I receive?
The number depends on the application and the lenders’ responses. One genuinely financeable proposal may be more valuable than several unapproved simulations. The broker seeks a useful comparison, not an artificial number of offers.
A bank has rejected my application. Can you still help?
Potentially. The broker must first understand the reason for the rejection. Some issues can be corrected or presented differently; others make the financing objectively too risky. No outcome can be guaranteed before the full analysis.
Do I need to have already found a property?
No. You can contact us to assess your budget before you start viewing properties. Once a specific property has been found, however, the lender will still need to value it before definitively confirming the financing.
Can I also use the service for a second home or a rental investment?
Yes. These projects require a specific analysis. Equity, the loan-to-value ratio, recognised income and the list of lenders may differ from those for a primary residence.
Am I required to accept the offer presented?
No. The initial consultation, preliminary analysis and introduction are all without obligation. You make the final decision after receiving the explanations relating to the proposal.
Have your project analysed before choosing your mortgage
Property financing often commits you for several years. The choice should not be based on an advertised rate or the first positive response received.
pretimmobilier.ch starts by understanding your project. We then select the most suitable partner, who prepares the application, identifies relevant lenders, negotiates the terms and supports you through to completion of the loan when it is approved.
You benefit from this expertise free of charge without giving up your freedom to decide.
They obtained their mortgage with us
Find our professional mortgage brokers throughout Switzerland
Zoomez et cliquez sur le canton désiré.
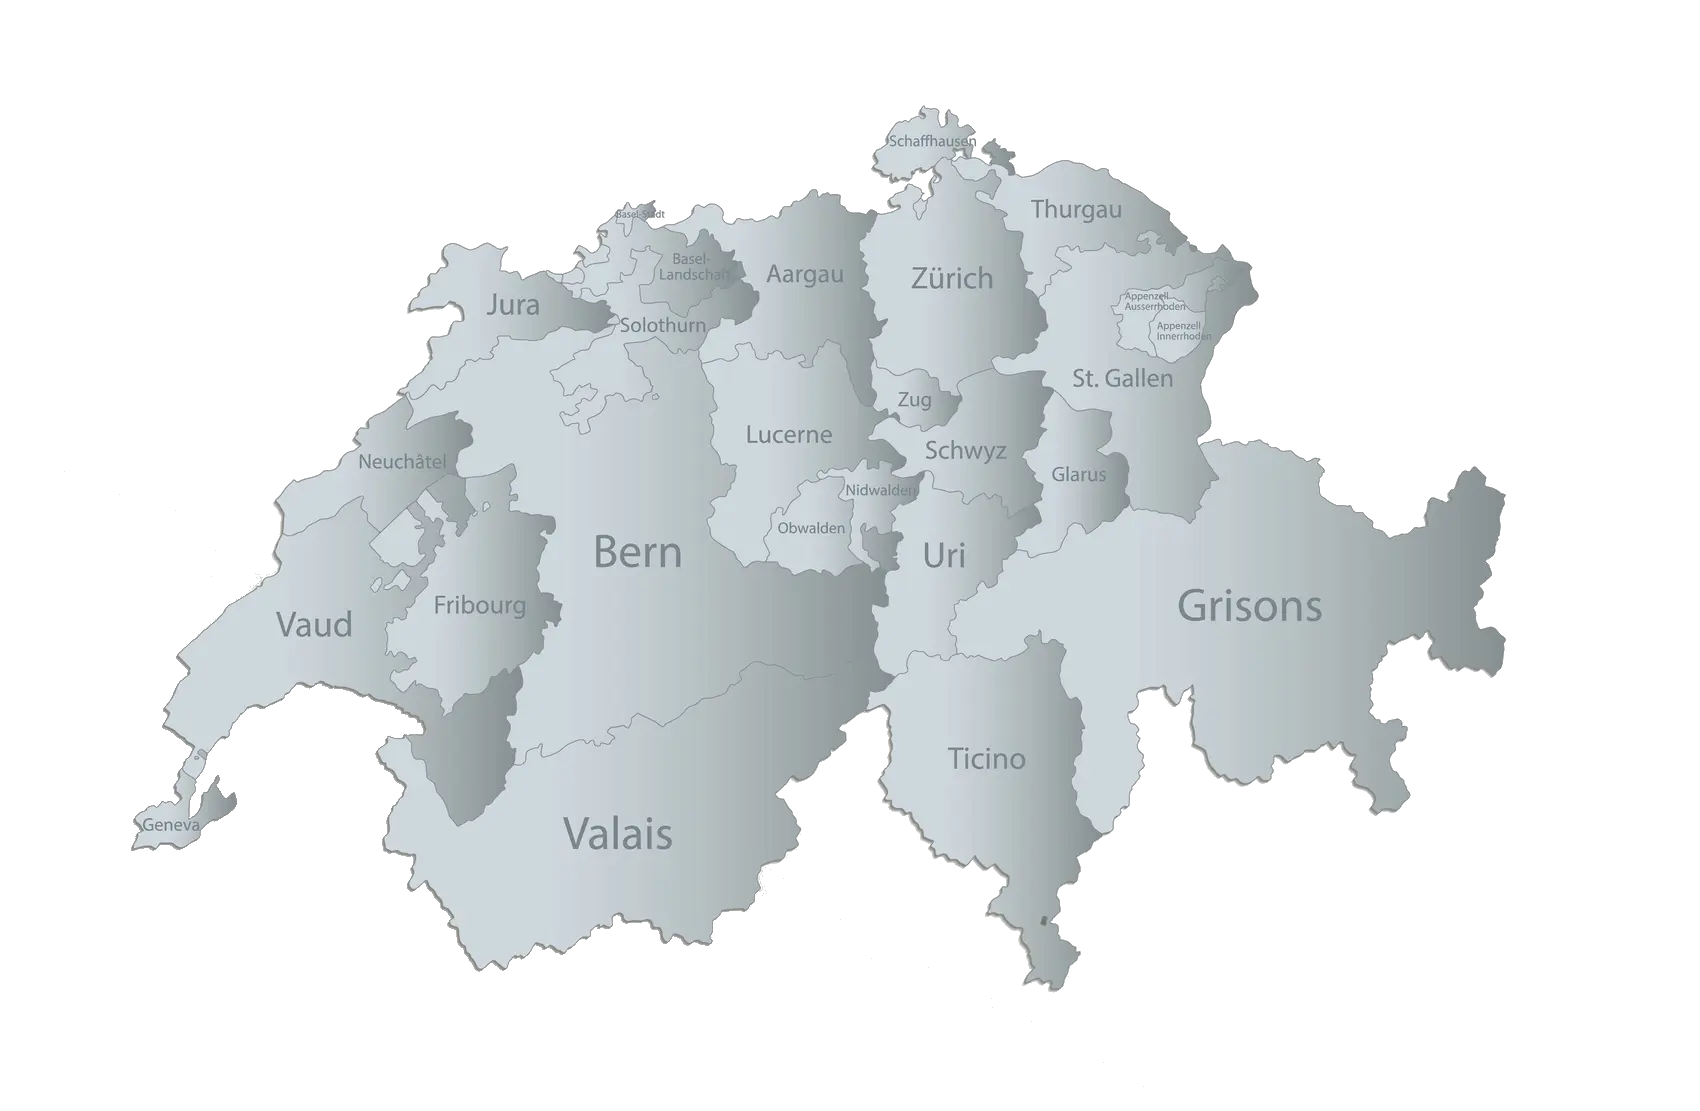
Your mortgage brokers by region
Canton de Schaffhouse : crédit hypothécaire au meilleur taux
Canton de Schaffhouse: hypothèque la plus avantageuse avec un courtier indépendant; comparez les prêteurs et financez votre bien aux meilleures conditions.
Canton de Zoug : votre hypothèque aux meilleures conditions
Dans le canton de Zoug, trouvez une hypothèque solide avec un courtier indépendant : comparez les prêteurs pour financer votre bien aux meilleures conditions
Canton de Schwytz: Prêt immobilier aux meilleures conditions
Trouvez votre crédit hypothécaire dans le canton de Schwytz avec un courtier indépendant: comparez les offres et obtenez les meilleures conditions de prêt.
Canton de Nidwald : hypothèque aux meilleures conditions
Trouvez votre crédit hypothécaire dans le canton de Nidwald avec un courtier indépendant : comparez les banques et obtenez les meilleures conditions du marché.
Trouver le meilleur prêt immobilier dans le canton d’Obwald
Trouver votre prêt immobilier aux meilleures conditions dans le canton d’Obwald grâce à un courtier hypothécaire qui vous aider à faire accepter votre dossier.
Canton d’Argovie: Financer votre achat immobilier rapidement
Financez votre bien immobilier dans le canton d’Argovie : prix attractifs, types d’hypothèques, fonds propres, calculateur et conseils pour comparer les offres
Canton de Bâle : Crédit immobilier aux meilleures conditions
Financez votre bien dans le canton de Bâle-Ville ou le canton de Bâle-Campagne: comparez les hypothèques, estimez vos fonds propres et préparez votre dossier
Canton Soleure: obtenez votre crédit hypothécaire rapidement
Canton de Soleure: comment chercher votre prêt hypothécaire pour obtenir les meilleures conditions. Préparer votre dossier avec un courtier professionnel.
Canton de Thurgovie : trouvez votre prêt hypothécaire suisse
Canton de Thurgovie – Obtenez votre crédit hypothécaire rapidement et aux meilleures conditions du marché. Assemblez votre dossier avec un courtier professionnel.
Immo Appenzell: les hypothèques dans la région d’Appenzell
Immo Appenzell: trouvez votre hypothèque aux meilleures conditions à Rhodes-Intérieures ou Rhodes-Extérieures avec un courtier professionnel.
Canton de Glaris: trouvez votre prêt hypothécaire facilement
Canton de Glaris: obtenez votre hypothèque rapidement et aux meilleures conditions. Préparez votre dossier avec un courtier professionnel pour acheter.
Hypo St Gallen: votre prêt hypothécaire au meilleur taux
Immobilier St Gallen: préparez votre dossier hypo St Gallen et obtenez votre crédit hypothécaire aux meilleures conditions avec un courtier professionnel.
Canton Uri – Crédit hypothécaire au meilleur taux
Canton d’Uri : obtenez votre prêt hypothécaire au meilleur taux et préparez gratuitement votre dossier avec un courtier professionnel (Uri Immo).
Immobilier Grisons : obtenez votre prêt au meilleur taux
Immobilier Grisons : obtenez votre prêt hypothécaire au meilleur taux, notamment pour un appartement à Davos, avec l’aide d’un courtier professionnel.

Achat immobilier Lucerne: obtenir votre crédit hypothécaire
Achat immobilier à Lucerne: obtenez votre prêt hypothécaire rapidement et au meilleur taux. Préparez votre dossier avec un courtier professionnel local.
Immo Tessin: trouvez votre crédit hypothécaire au meilleur taux
Immo Tessin : obtenez votre prêt hypothécaire au meilleur taux grâce à nos courtiers spécialisés pour votre projet immobilier dans le canton du Tessin.
Hypothèque Zurich : achetez votre maison au meilleur taux
Achat maison Zurich ou appartement à Zurich : obtenez votre prêt hypothécaire au meilleur taux avec l’aide de nos courtiers spécialisés dans le canton.
Immobilier Jura: Trouver la meilleure hypothèque
Immobilier Jura : Découvrez les hypothèques disponibles dans le canton du Jura et comment vous préparez à acheter dans ce canton.
Courtier en hypothèque dans le canton de Vaud : votre prêt
Obtenez le meilleur taux pour votre prêt immobilier dans le canton de Vaud. Courtier gratuit, offres négociées, accompagnement complet et rapide.

Courtier hypothèque Sierre: Meilleur taux garanti
Crédit hypothécaire à Sierre : retrouvez ici comment un courtier professionnel local peut vous aider à obtenir le meilleur taux et les meilleures conditions.
Hypothèque à Berne : financez votre bien immobilier
Vous souhaitez acheter un bien immobilier à Berne ? Découvrez nos conseils et les solutions de prêts hypothécaires adaptées à vos besoins et budget.
Courtier hypothèque Yverdon-les-Bains : votre prêt sur mesure
Obtenez le meilleur taux pour votre prêt immobilier à Yverdon. Courtier gratuit, offres négociées, accompagnement complet et rapide.
Courtier hypothèque Lausanne : Meilleur taux garanti
Besoin d’un prêt immobilier à Lausanne ? Profitez d’un service de courtage gratuit pour obtenir la meilleure offre d’hypothèque du marché.
Courtier hypothèque Fribourg : accédez aux meilleurs taux
Comparez gratuitement les meilleures hypothèques à Fribourg ! Obtenez un financement adapté à votre projet avec nos courtiers experts.
The information presented on this page is general and does not constitute a credit offer, a guarantee of acceptance or a promise of an interest rate. The terms depend in particular on your financial situation, the property, the lender and the market at the time of application. The decision to grant financing rests exclusively with the financial institution. Tax, legal and pension consequences should, where necessary, be checked with qualified specialists.

